Loading...
Searching...
No Matches
roots.hpp File Reference
#include <randlib/math/constants.hpp>#include <algorithm>#include <cmath>#include <concepts>#include <functional>#include <limits>#include <stdexcept>#include <tuple>#include <type_traits>#include <utility>
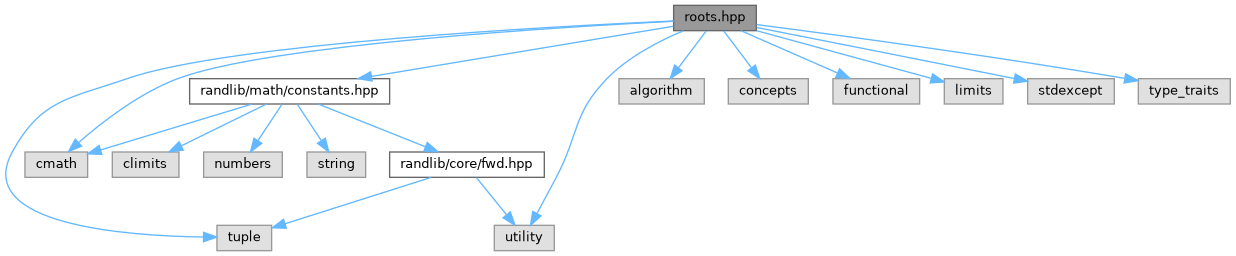
Include dependency graph for roots.hpp:
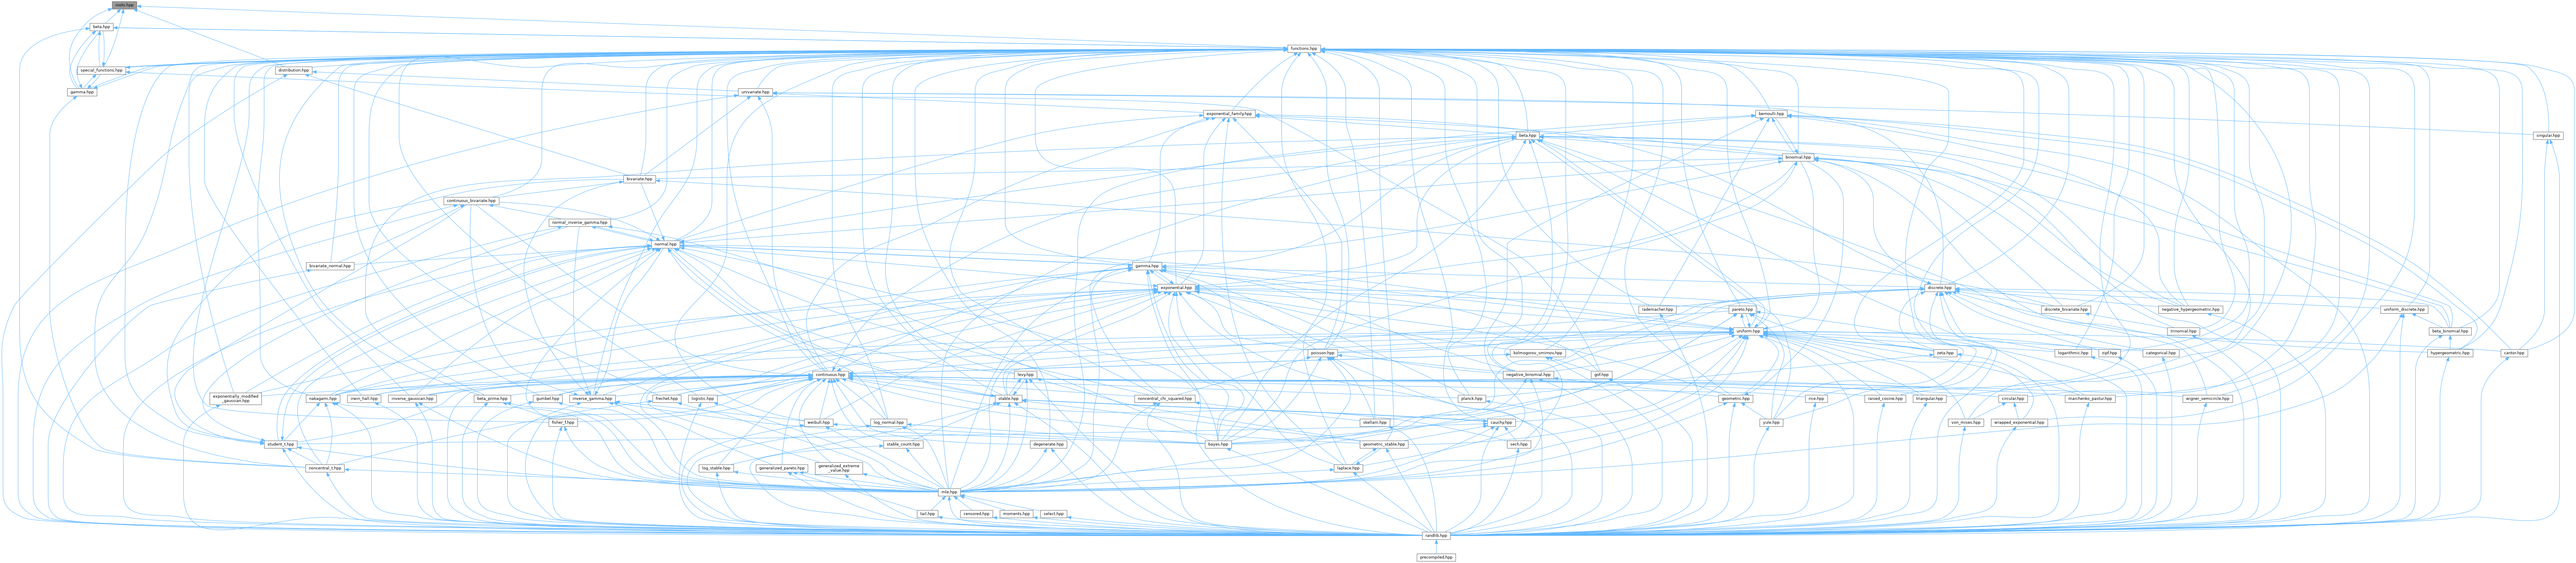
This graph shows which files directly or indirectly include this file:
Go to the source code of this file.
Namespaces | |
| namespace | randlib |
| namespace | randlib::math |
| Beta-related functions. | |
| namespace | randlib::math::detail |
Functions | |
| template<std::floating_point Real> | |
| bool | randlib::math::detail::bracketResolved (Real a, Real b) |
| |b - a| no longer resolvable at the relative precision of Real | |
| template<std::floating_point Real> | |
| Real | randlib::math::detail::safeDivide (Real numerator, Real denominator, Real fallback) |
| template<std::floating_point Real> | |
| Real | randlib::math::detail::secantStep (Real a, Real b, Real fa, Real fb) |
| template<std::floating_point Real> | |
| Real | randlib::math::detail::newtonQuadraticStep (Real a, Real b, Real d, Real fa, Real fb, Real fd, int steps) |
| template<std::floating_point Real> | |
| Real | randlib::math::detail::inverseCubicStep (Real a, Real b, Real d, Real e, Real fa, Real fb, Real fd, Real fe) |
| template<std::floating_point Real, class F > | |
| std::pair< Real, Real > | randlib::math::toms748 (const F &f, Real a, Real b, Real fa, Real fb, int maxIterations=200) |
| Bracketing root finder of Alefeld, Potra and Shi (ACM TOMS algorithm 748): inverse cubic and Newton-quadratic interpolation steps, a double-length secant step and bisection whenever the bracket does not shrink by half; it converges like Brent's method at worst and faster on smooth functions. | |
| template<std::floating_point Real = double, class F > | |
| Real | randlib::math::findRoot (const F &f, std::type_identity_t< Real > a, std::type_identity_t< Real > b, int maxIterations=200) |
| template<typename RealType > | |
| bool | randlib::math::findRootNewtonFirstOrder (const std::function< DoublePair(RealType)> &funPtr, RealType &root, long double funTol=1e-10, long double stepTol=1e-6) |
| Newton's root-finding procedure, using first derivative. | |
| template<typename RealType > | |
| bool | randlib::math::findRootNewtonSecondOrder (const std::function< DoubleTriplet(RealType)> &funPtr, RealType &root, long double funTol=1e-10, long double stepTol=1e-6) |
| Newton's root-finding procedure, using first and second derivatives. | |
| bool | randlib::math::findRootNewtonFirstOrder2d (const std::function< DoublePair(DoublePair)> &funPtr, const std::function< std::tuple< DoublePair, DoublePair >(DoublePair)> &gradPtr, DoublePair &root, long double funTol=1e-10, long double stepTol=1e-6) |
| Newton's root-finding procedure for 2 functions of 2 parameters, using Jacobian matrix. | |
