Loading...
Searching...
No Matches
optimize.hpp File Reference
#include <randlib/math/constants.hpp>#include <algorithm>#include <cmath>#include <concepts>#include <functional>#include <limits>#include <numeric>#include <span>#include <tuple>#include <vector>
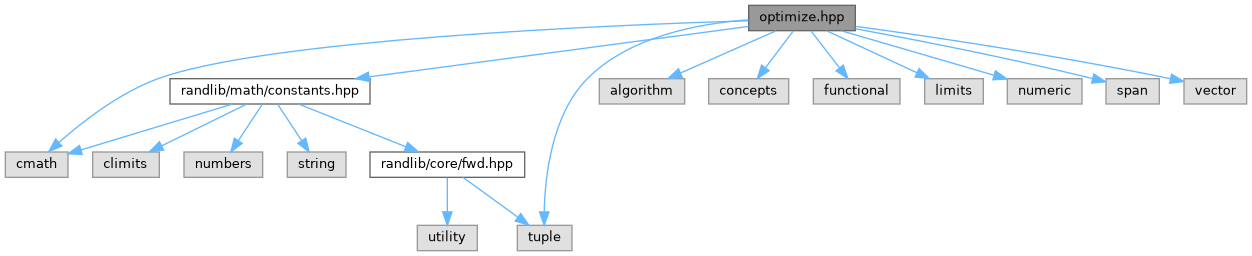
Include dependency graph for optimize.hpp:
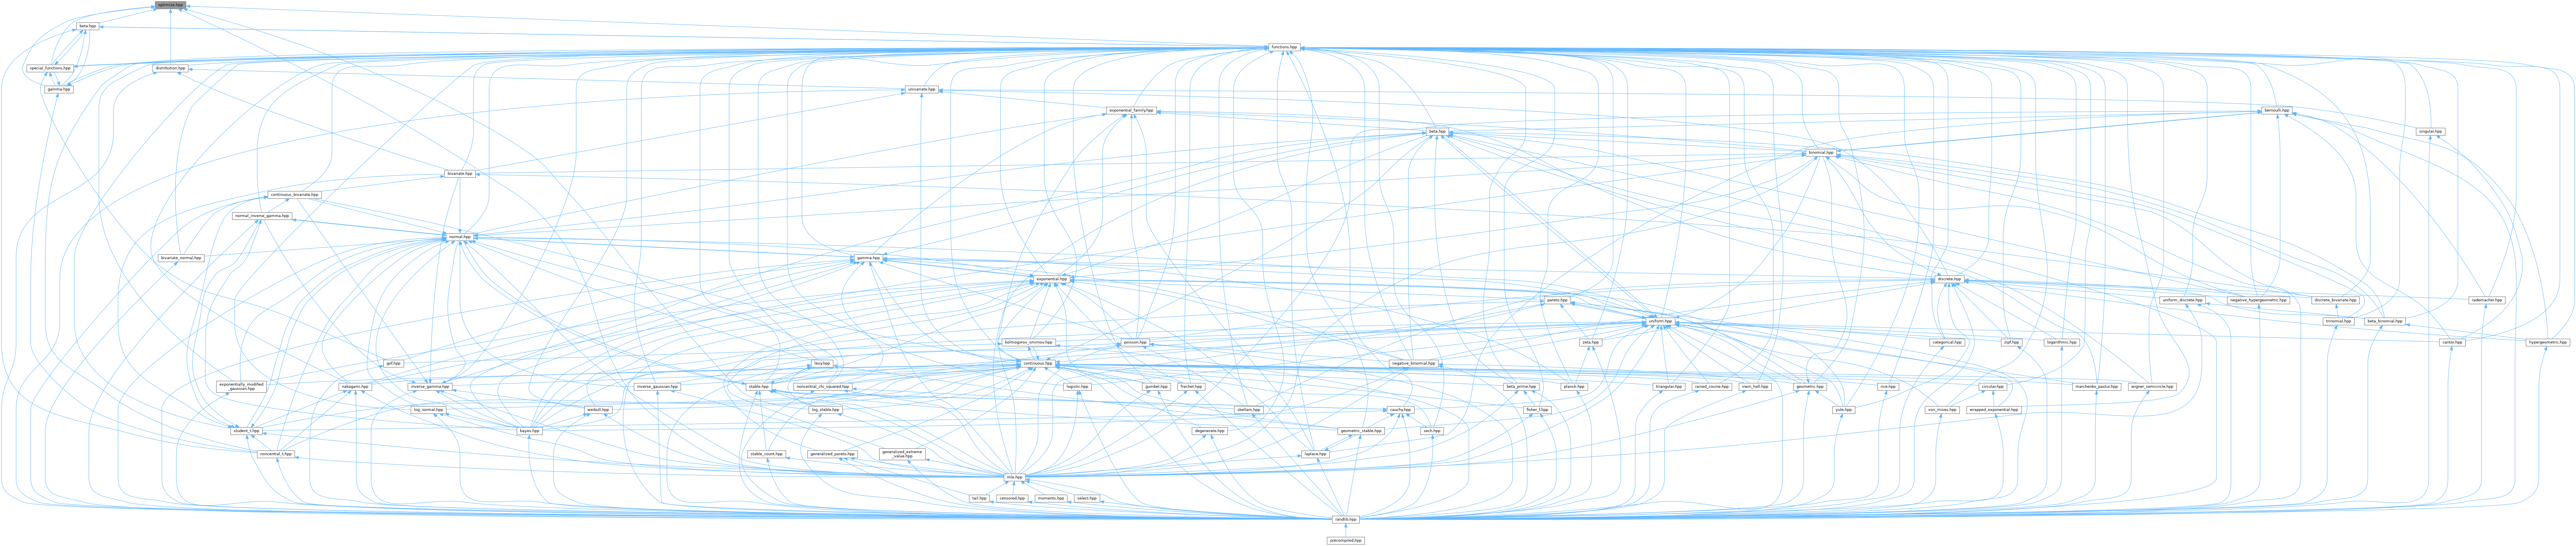
This graph shows which files directly or indirectly include this file:
Go to the source code of this file.
Classes | |
| struct | randlib::math::MinimizeResult< Real > |
| The MinimizeResult struct Outcome of a multivariate minimization. More... | |
Namespaces | |
| namespace | randlib |
| namespace | randlib::math |
| Beta-related functions. | |
Functions | |
| template<typename RealType > | |
| double | randlib::math::parabolicMinimum (RealType a, RealType b, RealType c, double fa, double fb, double fc) |
| template<typename RealType > | |
| bool | randlib::math::findMin (const std::function< double(RealType)> &funPtr, const Triplet< RealType > &abc, double &fx, RealType &root, double epsilon) |
| Combined Brent's method. | |
| template<typename RealType > | |
| bool | randlib::math::findMin (const std::function< double(RealType)> &funPtr, RealType closePoint, RealType &root, long double epsilon=1e-8) |
| Combined Brent's method. | |
| template<std::floating_point Real = double, class F > | |
| MinimizeResult< Real > | randlib::math::nelderMead (const F &f, std::vector< Real > start, Real tolerance=1e-10, int maxIterations=20000) |
| Downhill simplex method of Nelder and Mead with the dimension-dependent coefficients of Gao and Han (2012). | |
| template<std::floating_point Real = double, class F > | |
| std::vector< Real > | randlib::math::numericalGradient (const F &f, const std::vector< Real > &x) |
| template<std::floating_point Real = double, class F > | |
| std::vector< std::vector< Real > > | randlib::math::numericalHessian (const F &f, const std::vector< Real > &x) |
| template<std::floating_point Real = double, class F > | |
| MinimizeResult< Real > | randlib::math::bfgs (const F &f, std::vector< Real > start, Real tolerance=1e-8, int maxIterations=1000) |
| Quasi-Newton minimization of Broyden, Fletcher, Goldfarb and Shanno with central-difference gradients and a backtracking line search under the Armijo condition. | |
