The GammaDistribution class
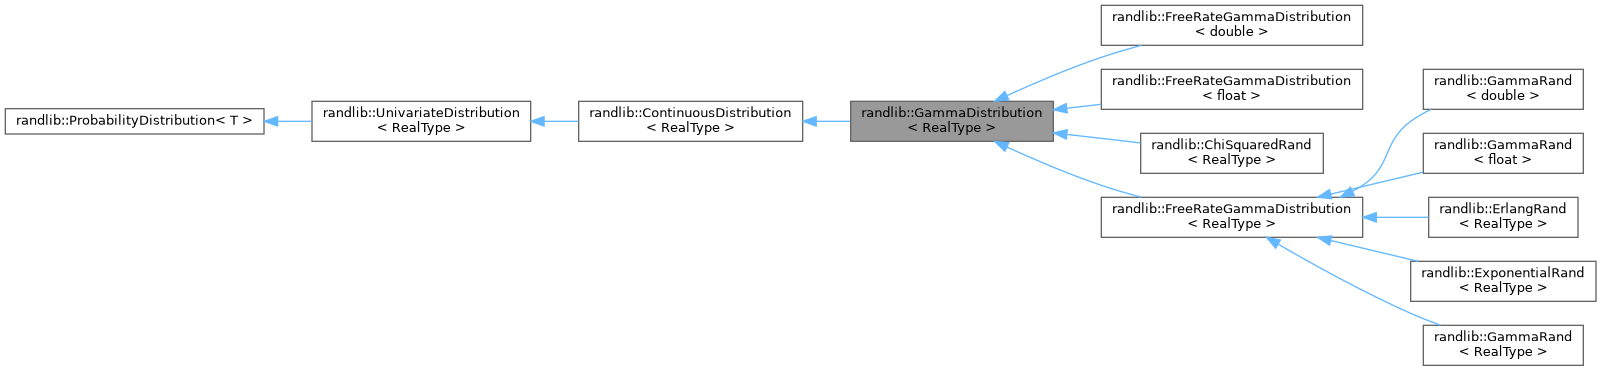
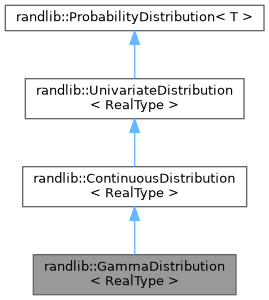
Abstract class for Gamma distribution.
More...
#include <gamma.hpp>
Public Member Functions | |
| virtual | ~GammaDistribution () |
| Support | SupportType () const override |
| RealType | MinValue () const override |
| RealType | MaxValue () const override |
| double | GetShape () const noexcept |
| double | GetScale () const noexcept |
| double | GetRate () const noexcept |
| double | GetLogGammaShape () const noexcept |
| double | GetLogShape () const noexcept |
| double | GetDigammaShape () const noexcept |
| double | GetLogRate () const noexcept |
| double | f (const RealType &x) const override |
| double | logf (const RealType &x) const override |
| double | F (const RealType &x) const override |
| double | logF (const RealType &x) const |
| double | S (const RealType &x) const override |
| double | logS (const RealType &x) const |
| template<std::uniform_random_bit_generator G> | |
| RealType | operator() (G &g) const |
| long double | Mean () const override |
| long double | GeometricMean () const |
| long double | Variance () const override |
| long double | GeometricVariance () const |
| RealType | Mode () const override |
| Mode is the value, which has the largest probability to happen, or, in the case of continuous distribution, has the largest value of density function. | |
| RealType | Median () const override |
| long double | Skewness () const override |
| long double | ExcessKurtosis () const override |
 Public Member Functions inherited from randlib::ContinuousDistribution< RealType > | |
| virtual | ~ContinuousDistribution () |
| void | ProbabilityDensityFunction (std::span< const RealType > x, std::span< double > y) const |
| fill vector y with f(x) | |
| void | LogProbabilityDensityFunction (std::span< const RealType > x, std::span< double > y) const |
| fill vector y with logf(x) | |
| double | Hazard (const RealType &x) const override |
| double | LikelihoodFunction (std::span< const RealType > sample) const override |
| double | LogLikelihoodFunction (std::span< const RealType > sample) const override |
| bool | KolmogorovSmirnovTest (std::span< const RealType > orderStatistic, double alpha) const |
| Public Member Functions inherited from randlib::UnivariateDistribution< RealType > | |
| virtual | ~UnivariateDistribution () |
| bool | isLeftBounded () const |
| bool | isRightBounded () const |
| RealType | Quantile (double p) const |
| RealType | Quantile1m (double p) const |
| void | QuantileFunction (std::span< const double > p, std::span< RealType > y) const |
| void | QuantileFunction1m (std::span< const double > p, std::span< RealType > y) const |
| std::complex< double > | CF (double t) const |
| void | CharacteristicFunction (std::span< const double > t, std::span< std::complex< double > > y) const |
| void | HazardFunction (std::span< const RealType > x, std::span< double > y) const |
| virtual long double | Kurtosis () const |
| virtual long double | SecondMoment () const |
| virtual long double | ThirdMoment () const |
| virtual long double | FourthMoment () const |
| Public Member Functions inherited from randlib::ProbabilityDistribution< T > | |
| virtual | ~ProbabilityDistribution ()=default |
| virtual std::string | Name () const =0 |
| virtual double | F (const T &x) const =0 |
| void | CumulativeDistributionFunction (std::span< const T > x, std::span< double > y) const |
| virtual double | S (const T &x) const |
| void | SurvivalFunction (std::span< const T > x, std::span< double > y) const |
| template<std::uniform_random_bit_generator G> | |
| T | operator() (G &g) const |
| Draws a variate with the given engine through the virtual interface. | |
| T | Variate () const |
| Uses the engine of this object, so it is not thread-safe for one object; use operator() with one engine per thread instead. | |
| void | Sample (std::span< T > outputData) const |
| Fills the output with variates drawn with the engine of this object. | |
| template<std::uniform_random_bit_generator G> | |
| void | Sample (G &g, std::span< T > outputData) const |
| Fills the output with variates drawn with the given engine. | |
| void | Reseed (std::uint64_t seed) |
Static Public Member Functions | |
| template<std::uniform_random_bit_generator G> | |
| static RealType | StandardVariate (double shape, G &g) |
| template<std::uniform_random_bit_generator G> | |
| static RealType | Variate (double shape, double rate, G &g) |
| Static Public Member Functions inherited from randlib::UnivariateDistribution< RealType > | |
| static long double | GetSampleSum (std::span< const RealType > sample) |
| static long double | GetSampleMean (std::span< const RealType > sample) |
| static long double | GetSampleLogMean (std::span< const RealType > sample) |
| static long double | GetSampleVariance (std::span< const RealType > sample, double mean) |
| static long double | GetSampleLogVariance (std::span< const RealType > sample, double logMean) |
| static LongDoublePair | GetSampleMeanAndVariance (std::span< const RealType > sample) |
| static LongDoublePair | GetSampleLogMeanAndVariance (std::span< const RealType > sample) |
| static std::tuple< long double, long double, long double, long double > | GetSampleStatistics (std::span< const RealType > sample) |
Protected Member Functions | |
| GammaDistribution (double shape, double rate) | |
| void | SetParameters (double shape, double rate) |
| void | SetShape (double shape) |
| SetShape. | |
| Protected Member Functions inherited from randlib::ContinuousDistribution< RealType > | |
| ContinuousDistribution () | |
| std::complex< double > | integrateCharacteristicFunction (double t) const |
| long double | ExpectedValue (const std::function< double(RealType)> &funPtr, RealType minPoint, RealType maxPoint) const override |
| RealType | searchQuantile (double p, bool upperTail, RealType guess, double relativeStep=1e-3) const |
| Deterministic root search for the quantile: brackets the root, starting from the guess when it is finite, then refines it with the Illinois variant of regula falsi (on a logarithmic scale for small p), falling back to bisection whenever the bracket does not halve. | |
| Protected Member Functions inherited from randlib::UnivariateDistribution< RealType > | |
| UnivariateDistribution () | |
| Protected Member Functions inherited from randlib::ProbabilityDistribution< T > | |
| std::string | toStringWithPrecision (const double a_value, const int n=6) const |
| ProbabilityDistribution ()=default | |
| DefaultEngine & | engine () const |
| virtual void | sample (detail::EngineRef g, std::span< T > outputData) const |
| Fills the output with variate(g); distributions with a faster bulk algorithm override it. | |
| fit_error | fitError (FitErrorCode code, const std::string &explanation) const |
Protected Attributes | |
| double | alpha = 1 |
| shape α | |
| double | beta = 1 |
| rate β | |
| double | theta = 1 |
| scale θ = 1/β | |
| double | lgammaAlpha = 0 |
| log(Γ(α)) | |
| double | pdfCoef = 0 |
| α * log(β) - log(Γ(α)) | |
| double | logAlpha = 0 |
| log(α) | |
| double | logBeta = 0 |
| log(β) | |
| double | digammaAlpha = -randlib::consts::egamma |
| ψ(α) | |
Additional Inherited Members | |
| Public Types inherited from randlib::ProbabilityDistribution< T > | |
| using | value_type = T |
| Static Protected Member Functions inherited from randlib::UnivariateDistribution< RealType > | |
| static bool | allElementsAreNotGreaterThan (RealType value, std::span< const RealType > sample) |
| static bool | allElementsAreNotSmallerThan (RealType value, std::span< const RealType > sample) |
| static bool | allElementsAreNonNegative (std::span< const RealType > sample) |
| static bool | allElementsArePositive (std::span< const RealType > sample) |
| Static Protected Attributes inherited from randlib::ProbabilityDistribution< T > | |
| static constexpr size_t | MAX_ITER_REJECTION = detail::MAX_ITER_REJECTION |
| MAX_ITER_REJECTION upper boundary for maximum amount of iterations in rejection methods one thousand should be enough to be sure there is a bug (or rejection method is too slow to be used) | |
| static constexpr char | POSITIVITY_VIOLATION [] = "All elements should be positive" |
| static constexpr char | NON_NEGATIVITY_VIOLATION [] = "All elements should be non-negative" |
| static constexpr char | UPPER_LIMIT_VIOLATION [] = "No element should be greater than " |
| static constexpr char | LOWER_LIMIT_VIOLATION [] = "No element should be smaller than " |
Detailed Description
class randlib::GammaDistribution< RealType >
The GammaDistribution class
Abstract class for Gamma distribution.
f(x | α, β) = β^α / Γ(α) * x^(α-1) * exp(-βx), where Γ(α) denotes Gamma function
Notation X ~ Γ(α, β)
Related distributions:
σX ~ Γ(α, σβ)
If X ~ Γ(1, β), then X ~ Exp(β)
If X ~ Γ(0.5 * n, 0.5), then X ~ χ^2(n)
If X ~ Γ(k, β) for integer k, then X ~ Erlang(k, β)
Constructor & Destructor Documentation
◆ GammaDistribution()
|
protected |
◆ ~GammaDistribution()
|
inlinevirtual |
Member Function Documentation
◆ ExcessKurtosis()
|
overridevirtual |
- Returns
- E[((X - μ) / σ) ^ 4] - 3 (fourth moment around the mean divided by the square of the variance of the probability distribution minus 3)
var is finite, so is mu
Reimplemented from randlib::UnivariateDistribution< RealType >.
◆ f()
|
overridevirtual |
- Parameters
-
x
- Returns
- probability density function
Reimplemented from randlib::ContinuousDistribution< RealType >.
◆ F()
|
override |
◆ GeometricMean()
| long double randlib::GammaDistribution< RealType >::GeometricMean | ( | ) | const |
- Returns
- E[ln(X)]
◆ GeometricVariance()
| long double randlib::GammaDistribution< RealType >::GeometricVariance | ( | ) | const |
- Returns
- Var(ln(X))
◆ GetDigammaShape()
|
inlinenoexcept |
- Returns
- ψ(α)
◆ GetLogGammaShape()
|
inlinenoexcept |
- Returns
- log(Γ(α))
◆ GetLogRate()
|
inlinenoexcept |
- Returns
- log(β)
◆ GetLogShape()
|
inlinenoexcept |
- Returns
- log(α)
◆ GetRate()
|
inlinenoexcept |
- Returns
- β
◆ GetScale()
|
inlinenoexcept |
- Returns
- θ = 1/β
◆ GetShape()
|
inlinenoexcept |
- Returns
- α
◆ logF()
| double randlib::GammaDistribution< RealType >::logF | ( | const RealType & | x | ) | const |
◆ logf()
|
overridevirtual |
- Parameters
-
x
- Returns
- logarithm of probability density function
Implements randlib::ContinuousDistribution< RealType >.
◆ logS()
| double randlib::GammaDistribution< RealType >::logS | ( | const RealType & | x | ) | const |
◆ MaxValue()
|
inlineoverridevirtual |
- Returns
- maximum possible value that can be achieved by random variable
Implements randlib::ProbabilityDistribution< T >.
◆ Mean()
|
overridevirtual |
- Returns
- E[X]
Implements randlib::UnivariateDistribution< RealType >.
◆ Median()
|
overridevirtual |
- Returns
- such x that F(x) = 0.5
Reimplemented from randlib::UnivariateDistribution< RealType >.
◆ MinValue()
|
inlineoverridevirtual |
- Returns
- minimum possible value that can be achieved by random variable
Implements randlib::ProbabilityDistribution< T >.
◆ Mode()
|
overridevirtual |
Mode is the value, which has the largest probability to happen, or, in the case of continuous distribution, has the largest value of density function.
- Returns
- mode. In case, when it's not unique, return any of them.
Reimplemented from randlib::ContinuousDistribution< RealType >.
◆ operator()()
| RealType randlib::GammaDistribution< RealType >::operator() | ( | G & | g | ) | const |
◆ S()
|
override |
◆ SetParameters()
|
protected |
- Parameters
-
shape α rate β
set constants for generator
◆ SetShape()
|
protected |
SetShape.
- Parameters
-
shape α
◆ Skewness()
|
overridevirtual |
- Returns
- E[((X - μ) / σ) ^ 3] where μ is central moment and σ is standard deviation
var is finite, so is mu
Reimplemented from randlib::UnivariateDistribution< RealType >.
◆ StandardVariate()
|
static |
- Parameters
-
shape α g uniform random bit generator
- Returns
- gamma variate with shape α and unity rate
◆ SupportType()
|
inlineoverridevirtual |
- Returns
- type of support
Implements randlib::UnivariateDistribution< RealType >.
◆ Variance()
|
overridevirtual |
- Returns
- Var(X)
Implements randlib::UnivariateDistribution< RealType >.
◆ Variate()
|
static |
- Parameters
-
shape α rate β g uniform random bit generator
- Returns
- gamma variate with shape α and rate β
Member Data Documentation
◆ alpha
|
protected |
shape α
◆ beta
|
protected |
rate β
◆ digammaAlpha
|
protected |
ψ(α)
◆ lgammaAlpha
|
protected |
log(Γ(α))
◆ logAlpha
|
protected |
log(α)
◆ logBeta
|
protected |
log(β)
◆ pdfCoef
|
protected |
α * log(β) - log(Γ(α))
◆ theta
|
protected |
scale θ = 1/β
The documentation for this class was generated from the following file:
